

 Some of the links on this site may be affiliate links. ICOBench may receive advertising commissions when users visit recommended platforms via our affiliate links, at no additional cost to you. All recommendations are based on a comprehensive review process.
In 2026, crypto CeFi (centralized finance) platforms offer some of the most accessible ways for cryptocurrency holders to generate passive income without navigating smart contracts, impermanent loss, or complicated DeFi systems. Unlike staking or decentralized protocols, CeFi services function more like traditional savings or fixed-deposit accounts, as you typically deposit supported cryptocurrencies or stablecoins with a regulated or institutional-grade custodian, and the platform lends or deploys those assets to generate yield that is passed back to you as interest.
Rates remain significantly higher than traditional bank savings in most jurisdictions, driven by demand for crypto-backed credit, institutional borrowing, and specialized strategies. Leading platforms emphasize daily or flexible compounding, insurance-backed custody (often via Fireblocks or similar institutional providers), independent audits, and transparent proof-of-reserves or open-book reporting. However, availability often varies by country due to evolving regulations, such as MiCA in Europe and ongoing US restrictions on certain providers.
This guide focuses exclusively on established CeFi products that enable you to earn interest on your crypto in 2026. We’ll review five leading platforms and consider their rates, features, strengths, and limitations, so you can choose the ideal service for your needs right now.
Key Takeaways
- CeFi platforms let you earn interest on crypto without using DeFi or staking services.
- CoinDepo currently offers the highest crypto interest rates, with up to 23% APR on stablecoins.
- Longer fixed terms usually deliver significantly higher interest rates.
- Stablecoins typically yield more than Bitcoin or Ethereum on most platforms.
- Always check country availability and each platform’s live rates before committing funds.
The Best Platforms to Earn Interest on Your Crypto: Our Top Picks
The platforms listed here offer a strong range of features, supported assets, and crypto interest rates. No matter your specific preferences, you’ll find a suitable choice among these options:
- CoinDepo: Earn up to 23% on crypto savings with a compound interest account.
- YouHodler: Earn crypto interest with flexible yields and high-LTV lending.
- Nexo: Established option with tiered yields and daily compounding.
- Binance Earn: Simple exchange-connected crypto interest platform for easy accessibility.
- Ledn: Transparent and conservative stablecoin yields.
Below, we’ll take a closer look at each of these platforms, so you can pick the one that’s best for you.
1. CoinDepo – Earn Up to 23% on Crypto Savings With a Compound Interest Account
CoinDepo has made a name for itself as one of the highest-yielding CeFi platforms in 2026, and mainly specializes in straightforward compound interest accounts. Users deposit major cryptocurrencies or stablecoins, and can select from six payout frequencies: daily (current), weekly, monthly, quarterly, semi-annually, or annually. Longer terms unlock higher fixed APRs.
Stablecoins such as USDT, USDC, and DAI currently offer APRs of 17–23% depending on the selected term, while gold-backed tokens (PAXG, XAUt) are in the same range. Major assets (including BTC, ETH, BNB, XRP, SOL, DOGE, ADA, and others) earn a 12–18% APR. The platform’s native COINDEPO token can reach up to 25% APR, and governance was recently opened to COINDEPO token holders.
Interest compounds according to your chosen schedule and is paid in the deposited asset. Withdrawals of principal are available at any time, while accrued interest is paid only for completed periods. There are no deposit, withdrawal, or management fees.
Assets on CoinDepo are held in custody that is secured by Fireblocks and backed by insurance, and the platform has been audited by CertiK and Hacken. CoinDepo has approximately $240 million in assets under management, more than 113,000 active users, and an average yield paid of 15.8% APR. It also offers crypto-backed borrowing and is developing its own credit card.
The platform operates from Panama with regional offices, and serves users in most jurisdictions outside sanctioned lists.
| ✅ Pros | ❌ Cons |
|
|
2. YouHodler – Earn Crypto Interest With Flexible Yields and High-LTV Lending
YouHodler, a Swiss-based platform regulated as a financial intermediary in Switzerland and registered as a VASP in Italy, Spain, and Argentina, provides interest-generating accounts alongside its high-LTV crypto loans. Earning rates on major assets and stablecoins typically range from the mid-single digits to around 11–15% APY for USDT and USDC.
Payouts are typically weekly, with the option for more frequent credit. There is no minimum deposit, and funds remain accessible. Loyalty levels tied to trading volume or fixed-term commitments can boost payouts.
The YouHodler platform supports 50+ cryptocurrencies, while its custody system uses Ledger Vault alongside insurance coverage. YouHodler is not available in the US and faces certain MiCA-related limitations on specific stablecoins for EU users. Nonetheless, its dual focus on yield and borrowing (up to 90% LTV) can appeal to active traders looking for passive income and liquidity without selling their assets.
| ✅ Pros | ❌ Cons |
|
|
3. Nexo – Tiered Yields and Daily Compounding
Nexo is a popular CeFi brand that offers “Flexible Yield” (daily interest, withdraw anytime) and “Fixed-Term Yield” (higher rates for locks of 1–12 months) products. Top-tier rates for USDT and USDC on Flexible accounts reach up to 10.5%, and are higher for Fixed-Term users. BTC and ETH are lower, typically in the 4–7% range, depending on the user’s loyalty tier.
Rates are strongly influenced by Nexo’s Loyalty Program, and holding 10% of your portfolio value in NEXO tokens unlocks Platinum-tier benefits. Interest can be paid in-kind or in NEXO for an extra boost. The platform combines earn products with a credit line, exchange, and card, all supported by institutional-grade custody and regular audits. Daily compounding and automatic credit make the experience seamless.
Nexo exited the US market in late 2022 following regulatory action but announced its return in February 2026, and now offers yield and loan products to US customers through licensed partners.
| ✅ Pros | ❌ Cons |
|
|
4. Binance Earn – Simple Crypto Interest Option for Easy Accessibility
Binance Earn’s “Simple Earn” products (available in Flexible and Locked variations) prioritize ease of use and principal protection over the highest headline rates. Flexible USDT and USDC yields typically fall in the 2–7% APR range, while BTC yields are very low (around 0.3%) and ETH yields are in the low single digits. Locked products offer slightly higher fixed rates for set durations.
Rewards accrue every minute on Binance Earn’s “Flexible” products, and can be redeemed at any time. The service supports hundreds of assets and benefits from Binance’s massive liquidity and user base. Availability is broad but subject to regional restrictions and KYC.
Simple Earn is a convenient option for users already on Binance who want low-friction, low-risk yield on idle balances rather than maximizing returns.
| ✅ Pros | ❌ Cons |
|
|
5. Ledn – Transparent and Conservative Stablecoin Yields
Ledn focuses on transparency and Bitcoin-centric products. Its Growth Accounts for USDC and USDT offer 5% APY on balances below 100,000 and 6% APY above that threshold, and interest is generated primarily by lending to Ledn’s overcollateralized Bitcoin loan book. Accounts are open-term with free movement between “Growth” and “Transaction” accounts; the latter is held mostly in cold storage.
Ledn publishes monthly Open Book reports, emphasizes ring-fencing of Growth account assets, and does not offer yield on a wide range of altcoins. The platform has a strategic relationship with Tether and strong proof-of-reserves practices. Its rates are more conservative than high-yield competitors, making Ledn suitable for risk-conscious holders of stablecoins who value transparency and custody standards.
| ✅ Pros | ❌ Cons |
|
|
Comparing Our Top Platforms for Earning Interest on Crypto in 2026
The rates provided in the table below may vary over time, and are often tier- or term-dependent. Always verify live rates and eligibility on the platform you’re considering.
| Platform | Supported Cryptos | Lowest / Highest Typical APRs (Major Cryptos & Stablecoins) | Core Features | Supported Countries |
| CoinDepo | 30+ assets including BTC, ETH, SOL, USDT, USDC, DAI, PAXG, BNB, XRP, native COINDEPO token, and more | 12% / 23% | Compound Interest Accounts (6 term options), no fees, Fireblocks + insurance | Most jurisdictions except sanctioned lists |
| YouHodler | 50+ coins, including BTC, ETH, SOL, USDT, USDC | ~5–8% / ~11–15% | Weekly payouts, high-LTV loans, loyalty boosts | Switzerland, most EU/EEA countries, Argentina, and many others in Europe, Latin America, Asia, and the Middle East. Not available in the US or China (including Hong Kong / Macau) |
| Nexo | 30+ coins, including BTC, ETH, USDT, USDC, NEXO | ~2–5% / ~10.5–16% | Daily flexible + fixed-term accounts, loyalty tiers | Most countries with some exceptions (but strong in EU, UK, Latin America, Asia). Not available in Canada, Bulgaria, and sanctioned territories |
| Binance Earn | 300+ | ~0.3% (BTC) / ~4–7% | Simple Earn Flexible/Locked accounts, minute-by-minute accruals | Approximately 180+ countries. Restricted in the US, Canada, and OFAC-sanctioned countries (e.g. Iran, North Korea, Cuba, Syria). Features can vary by region |
| Ledn | Primarily USDC and USDT (BTC loans) | 5% / 6% | Growth accounts, Open Book transparency | Select countries only. Not available in the US, Canada, all EU countries, Switzerland, China, Russia, Ukraine, and a long list of other jurisdictions |
How to Earn Interest on Your Crypto With CoinDepo: Step-by-Step Guide
Step 1: Create Your Account
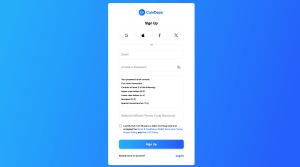
Go to the official CoinDepo website and click the “Sign Up” button. Enter your email address, set a strong password, and confirm the verification link sent to your inbox. You can also sign up using Google, Apple, or other supported social logins. The process takes under a minute.
Step 2: Complete Identity Verification
For this step, you’ll need to upload a government-issued ID (passport or national ID) along with a quick selfie. Approval is usually automated and arrives within minutes. Without full verification, deposit and withdrawal limits are restricted (typically to the equivalent of $500).
Step 3: Deposit Your Crypto or Stablecoins
Go to the “Earn” section, select the asset you want to deposit (USDT, USDC, BTC, ETH, etc.), and choose the correct network. Copy the unique deposit address generated for your account and send funds from an external wallet or exchange. Once the blockchain confirms the transaction, the assets will appear in your Current (daily) Compound Interest Account and begin earning immediately.
Step 4: Choose Your Compound Interest Account Type
From the Earn dashboard, you can open Weekly, Monthly, Quarterly, Semi-Annual, or Annual compound interest accounts and transfer funds into them from your Current account. Longer terms unlock higher fixed APRs. You can hold multiple accounts at the same time and move funds between them as needed.
Step 5: Monitor and Manage Your Funds
You can track your balance, accrued interest, and compounding schedule from your private dashboard. You can withdraw principal at any time (interest is paid only for completed periods) or open a credit line against your deposits without interrupting the yield.
Tips to Maximize the Interest on Your Crypto Savings
Getting the highest possible return on CeFi interest products requires more than simply depositing your funds and walking away. A few deliberate choices can meaningfully improve your effective yield over time.
First, match your account’s term length to your liquidity needs. On platforms such as CoinDepo, longer compounding periods (quarterly, semi-annual, or annual) deliver noticeably higher fixed APRs than daily or weekly accounts. If you won’t need the funds for several months (or even years), locking into a longer term is usually the single biggest rate booster available. Just remember that early withdrawals typically forfeit the interest for the incomplete period.
Second, prioritize stablecoins if you feel capital preservation is more important than speculative upside. USDT, USDC, and similar assets consistently offer the highest advertised rates on most CeFi platforms because the platforms face lower risk when managing dollar-pegged collateral. Major cryptocurrencies such as Bitcoin and Ethereum still produce solid yields, but they sit lower on the rate ladder.
Third, pay attention to loyalty or token incentives where they exist. Some platforms (including CoinDepo’s COINDEPO Advantage Program and Nexo’s loyalty tiers) reward users who hold a portion of the native token or elect to receive interest in that token. These boosts can add several percentage points, though they introduce additional price risk that should be sized carefully.
Fourth, avoid unnecessary friction and fees. Choose platforms with zero deposit and withdrawal fees for the assets you hold, and always double-check the correct blockchain network before sending funds. Network errors are among the most common and irreversible causes of crypto asset loss.
Finally, review rates and platform terms periodically, as they can change with market conditions, and only deposit what you can afford to leave in place according to the chosen term.
By combining longer terms where possible, favoring high-yielding stablecoins, taking advantage of available loyalty boosts, minimizing operational mistakes, and staying on top of the latest platform updates, most users can improve the returns they earn on their crypto savings.
How to Earn Interest on Your Crypto in 2026: Final Thoughts
The best CeFi crypto interest products in 2026 deliver attractive yields while maintaining user experiences that are often similar to those provided in the traditional finance industry. The five platforms reviewed in this guide illustrate how wide the spectrum has become. From high-APR compound interest accounts designed for maximum returns (CoinDepo) to simple exchange-related products (Binance Earn) that prioritize ease and liquidity, the option that makes the most sense will depend on what matters most to you right now.
In our view, CoinDepo currently stands out for its industry-leading fixed APRs (up to 23% on stablecoins), flexible compounding schedules, zero fees, and institutional custody standards. For holders seeking the highest risk-adjusted CeFi returns without DeFi complexity, we believe it is the strongest option among those considered here. As always, we also recommend that crypto investors understand counterparty risk, check live rates and terms on any platform’s official website ahead of time, and only deposit what you can afford to keep locked up or otherwise left at risk.